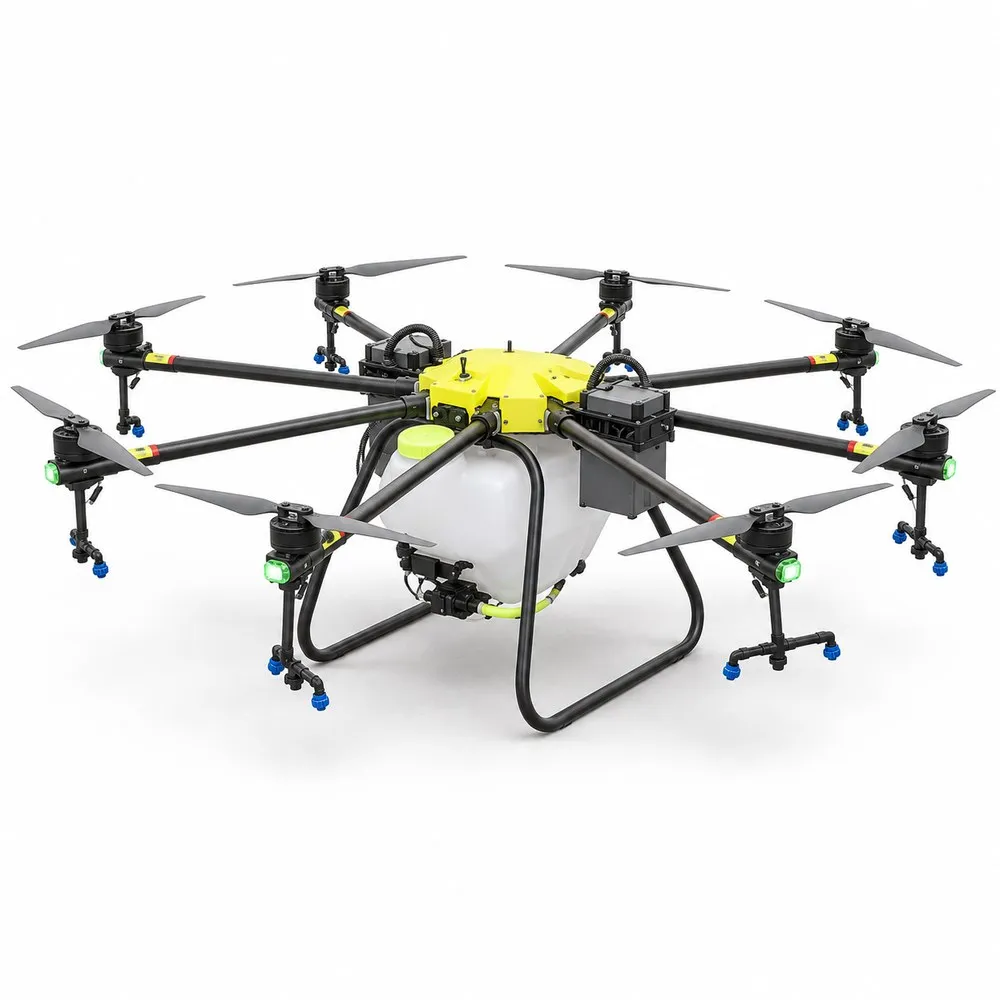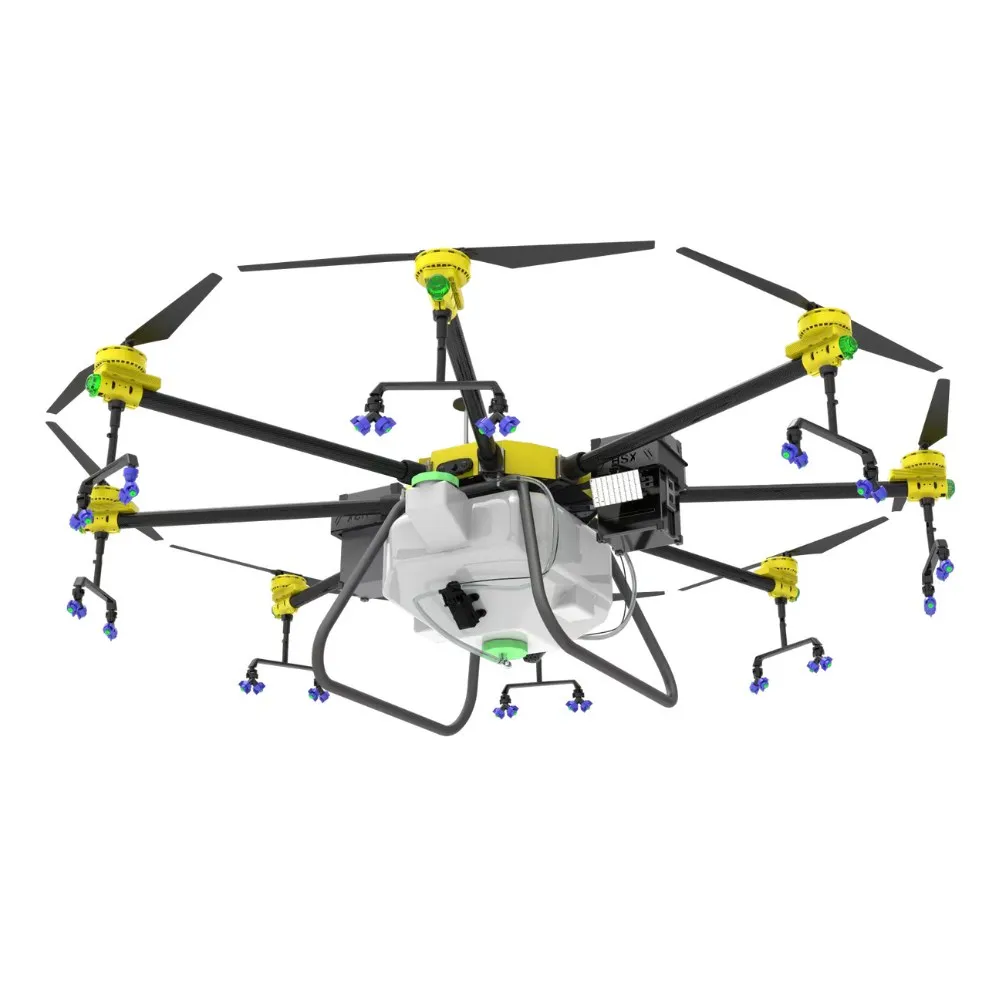
Short answer: You can pay for an agricultural drone with a bank loan, a lease, instalments from the seller, or a shared-risk deal with a supplier or partner. Extension guides agree on one point: leasing helps cash flow and flexibility, while buying tends to cost less over time if the machine lasts well past the loan. Lenders want proof of income, so bring a work plan and a full quote. Do the payback math before you sign, and ask your own bank for terms. We do not give financial advice or name lenders.
The four ways to pay
A spray drone is a business tool. The right choice depends on how many hours you will fly, how sure your income is, and what you own already.
| Option | How it works | Good when | Watch out for |
|---|---|---|---|
| Bank or development bank loan | You borrow an amount, pay it back with interest, and you own the drone | You will use the drone for many seasons | Fixed payments in a slow season; collateral; early repayment fees |
| Lease | You pay to use the drone for a set time; at the end you return it or buy it | You want lower starting cost or to test the business | Total cost can be higher; limits on use; who pays for repair |
| Instalments from the seller | You pay a deposit, then pay the rest in parts | You have some cash and a clear season plan | Terms are set by discussion; ownership rules; the seller may keep title until paid |
| Shared-risk or service deal | A partner, cooperative or supplier shares the cost; you pay from service income | You are new and have a customer group | Clear written split of income, repair and downtime |
Penn State Extension notes that owning can be the cost-effective choice once a lease ends, and that depreciation, variable costs and loan interest may be tax deductible in some systems. Tax rules differ in every country, so ask a local adviser.
What lenders look at
Lenders do not lend against a photograph of a drone. They lend against your ability to pay. Prepare these items:
- A short business plan: the crops, the area, the season, and the price per acre or hectare you expect.
- Names or letters from customers, a cooperative, or a past service record.
- A written quote for the whole package, not only the drone. Include batteries, charger or generator, spare parts and training.
- Proof of the aviation permit steps you have started, if your country requires them.
- Your own deposit, if you have one.
Manitoba guidance says financing mainly protects working capital. For a spray team this means you keep cash for fuel, chemicals, wages and insurance during the work season.
Match the schedule to the season
Drone work is seasonal. A team in a rice area may fly hard for a few months and then have little work. If a lender gives equal monthly payments, you must pay in the quiet months too. Ask whether the payments can be larger in the work season and smaller in the quiet months. Some lenders allow this for farm borrowers, but terms differ, so ask.
Battery life also matters. Supplier ratings for the smaller F10-30 series packs are 300 to 500 charge cycles, and real life depends on heat and use. A loan that runs far longer than your battery packs will leave you buying new packs while you still pay for the drone. Our battery guide explains how many sets to plan.
A payback example
Example (not a promise): A service team buys a mid-size drone package and wants to check if a loan is safe. All numbers below are made up to show the method. Use your own.
| Item (example) | Per season |
|---|---|
| Area sprayed | 1,000 acres |
| Fee you charge | 10 per acre, in your local currency |
| Income | 10,000 |
| Running costs (fuel, parts, battery wear, pilot wage, transport, insurance) | 5,500 |
| Left to pay the loan | 4,500 |
If the yearly loan payments are 4,000, the team has only 500 left, and one bad month can break the plan. If the payments are 2,500, the team has a safer margin. Test the plan again with 20 % fewer acres. If it still works, the loan is more realistic. Our business plan guide shows how to build the cost list, and the price guide explains what sits inside a drone quote.
Who to ask
Start with your own bank and any national or regional agricultural development bank. Cooperatives and farmer groups may also have a group scheme or a shared purchase plan. Ask the lender what it needs for equipment of this type, because some banks do not know spray drones yet. A written quote and a short explanation of the work help.
We do not name financing companies and do not give financial advice. For terms with FLYZOR, such as deposit, payment steps and delivery, we agree them with each dealer or buyer by discussion. See the dealer page or contact us with your plan, and ask for a quote for the F52 or F72 package you want to finance.